CMHC Lending Limit: Canada’s Housing Market Could Cool As Mortgage Backer Reaches Cap

This article appeared on the Huffington Post on January 31st, 2012 and was written by Craig Wong.

OTTAWA – A federal limit on the amount of loans Canada Mortgage and Housing Corp. is allowed to insure could lead to stricter lending conditions and a cooling of the housing market, TD Bank economist Sonya Gulati said Tuesday.

“It may serve to tighten the housing market,” Gulati said.

CMHC had insured $541 billion in loans at Sept. 30, compared with $501 billion a year earlier and $514 billion as of Dec. 31, 2010. The limit was raised to $600 billion in total outstanding insured amounts from $450 billion in 2008.

Although Ottawa could increase the limit, as it did in 2008 in the wake of the financial crisis, it may not want to if it thinks too many people are borrowing more than they should, Gulati said.

Canadian mortgage rates have been near record lows in recent months. Earlier this month, some of Canada’s biggest banks began advertising promotional ultra-low fixed rate mortgages at 2.99 per cent for five years.

“If there are indications from the government perspective that there is overheating, one of the mechanisms can be to change mortgage eligibility rules,” Gulati said.

“Another way is to restrict or to indirectly make getting a mortgage tougher.”

Homebuyers who put down less than 20 per cent are required to pay for mortgage default insurance.

However, financial institutions may also take out mortgage default insurance where the borrowers put down more than the minimum required to avoid the mandatory insurance. The move allows banks to more easily bundle the mortgages and raise money on the capital markets with covered bonds backed by the mortgages.

CMHC said Tuesday it has recently received an unexpected level of requests for large amounts of CMHC portfolio insurance, which allows lenders to buy insurance on pools of previously uninsured low ratio mortgages.

“To ensure equitable access to portfolio insurance within CMHC’s annual limits, an allocation process is being established which has caused some delays,” the federal agency said.

CMHC noted that it does not affect the availability of CMHC’s mortgage loan insurance for qualified home buyers and would not impact the cost of buying a house.

RBC economist Robert Hogue noted that the government could raise the CMHC limit, but it is walking a fine line to keep the housing market from slowing too much or overheating.

“We’re looking for a middle of the road kind of performance so it would be, policywise, a very delicate balance to strike,” he said.

“I’m sure any kind of signal that might spook the housing market would be considered very prudently and at the same time, if there is any sign the market is starting to demonstrate signs it is going overboard it might want to find ways to cool it.”

Finance Minister Jim Flaherty and Bank of Canada governor Mark Carney have been warning for months that Canadians have been racking up more debt than they can sustain as a result of a long period of ultra-low interest rates.

Ottawa has been tightening mortgage lending rules in recent years in the effort to limit the dangers of a crisis in the real estate market in Canada.

Last year, the federal government reduced the maximum amortization period for new government-backed insured high-ratio mortgages to 30 years from 35 years and cut the maximum amount Canadians can borrow in refinancing their mortgages to 85 per cent from 90 per cent.

The government has also withdrawn insurance backing on non-amortizing home equity lines of credit.
Link

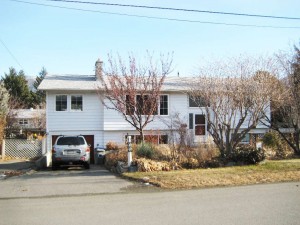
Featured Property: 1084 7th Street, North Kamloops, B.C. $329,900

1084 7th Ave North Kamloops Real EstateGreat North Kamloops home in a quiet neighbourhood close to shopping and transportation. Many recent updates including all windows, furnace (2 years), h/w tank (2 years), roof (8 years), flooring (hardwood, lino and carpet), paint, main floor bathroom and more. There is central a/c, all appliances are included and window coverings. 2 bedrooms on the main floor with a large family room off of the living room and dining room. The family room could be converted to an office/3rd bedroom. There are 2 bedrooms in the basement, with a 3 piece bathroom, large rec room, spacious laundry room and separate basement entry. Three fireplaces (2 wood, 1 gas), large yard with mature fruit trees, gardens and mostly fenced. There is a single car garage that is extra long. This is a great family home ready for its new family. All measurement are approx.
To view all homes for sale in Kamloops click here.

Featured Property: 327 Royal Avenue, North Kamloops Waterfront, B.C. $399,900

327 Royal Ave river front Property Kamloops BCRiverfront home minutes from downtown Kamloops with self contained inlaw suite. Many recent updates include: roof (4 years), h/w tank (3 years), all windows, all external doors, flooring, paint, bathroom in suite, window coverings and some appliances. There are 3 bedroom son the main floor and 2 bedrooms in the basement. Shared laundry on the main floor. This home is very well kept and shows well. The yard is fully fenced, and has beautiful views of the river and hills. There is a garden area, walnut trees and pear tree. Many nearby properties have private docks, which is a possibility for this property.

To view all homes for sale in Kamloops click here.

New Strata Regulations Good for Condo Buyers, Strata Property Act Reforms Long Overdue

This article appeared in the Vancouver Courier and was written by Royal Lepage City Centre Realtor Deb Abbey. The strata rules will also be applicable for Kamloops condos, townhouses and stratified properties. The changes are welcomed as it is always important that both the sellers and buyers are thoroughly informed. Article below:

2012 brings long awaited reform to the Strata Property Act that will provide greater security for more than one million strata property owners in the province.

But the biggest beneficiaries of the new regulations will be prospective buyers. Buying a condominium is a complex process in B.C. with buyers and their real estate agents playing the role of real estate detectives trying to suss out information about the state of the building envelope or running down maintenance and engineering reports trying to assess the true value of the property given any potential liabilities.

Until now, there haven’t been many, if any, safeguards for purchasers of condos that have been badly built or managed by their owners. Poor maintenance, inadequate or no budgeting for future repairs and replacements, and little or no transparency in terms of liabilities are issues with many strata corporations in Vancouver. That is about to change.

Among the changes, strata corporations will be required to prepare a depreciation report. The report will include a physical inventory of the strata’s common property including building systems such as the building envelope, roof, pipes and boilers. The report will also include an estimate of the cost of anticipated maintenance, repair and replacement of those common property items projected over 30 years.

And most important to prospective buyers, the strata corporations will be required to prepare financial forecasts of how the strata will fund those expenses from the contingency reserve fund or special levies. The report will have to be updated every three years and include an onsite inspection. The new regulations will be effective immediately but stratas will have two years to comply.

As a potential buyer, you’ll be provided with a copy of the most recent version of this report along with the Form B. Unfortunately, there’s a catch. Short-sighted stratas will be able to exempt themselves from this requirement with an annual 3/4 vote.

As a real estate agent, I hope that our industry widely adopts this report as a tool to assess risk and attribute value to the quality of management in strata corporations. Given the opportunity to buy or own a property that has future risk quantified and accounted for in this way, I know that I’d recommend those properties that have depreciation reports to my clients. The old adage “if you don’t measure it, you can’t manage it” has never been more appropriate.

Contingency reserve funds [CRF] have also gotten a boost from the new regulations. In the past, a 3/4 vote was required to make contributions to the CRF if it already exceeded 100 per cent of the annual operating expenses. The new regulations will allow strata corporations to make additional contributions to the CRF, once it reaches 25 per cent of the annual operating expenses, with a simple majority vote as part of the budget at the AGM.

This may sound like an insignificant bit of regulation but many stratas with looming expenses such as new roofs, windows or re-piping do not contribute enough to their CRFs to cover those costs and then have to levy significant special assessments that have condo owners rushing out to secure second mortgages.

And finally, there will be regulations requiring Form B to provide better disclosure to new strata owners. As of March 1, the rules and current budget of the strata corporation, Form J [the Rental Disclosure Statement] and the most recent Depreciation Report, will have to be attached to the Form B. The amendments will also require disclosure of how parking stalls and storage lockers are allocated to strata lots.

The changes fall short of the recommendations put forward by the British Columbia Real Estate Association and others. They don’t go nearly far enough in insulating prospective buyers from badly built or managed condos, but they will increase accountability and transparency for owners and potential buyers.

There’s bound to be some fallout from these regulations. The requirement to provide the depreciation report will be financially onerous for some strata corporations. Especially those with owners who qualified for mortgages with a minimum down payment and are just barely able to pay their strata fees as it is. I hope that the government recognizes that this will be a hardship and arranges some kind of low-interest financing tool so that as many stratas as possible can comply with the new regulations.

In terms of the market, I expect mortgage insurers and lenders will quickly adopt guidelines that give preference to strata corporations that are measuring and managing their risk. Over time, this will mean strata buildings that provide more disclosure will sell at a premium to those that don’t. And they’ll be worth it.

1 … 180 181 182 183 184 … 231